DSCR Loan Calculator
Enter the rent and the DSCR a lender asks for to see the largest loan and payment the rent supports.
Free · runs in your browser · nothing is uploaded
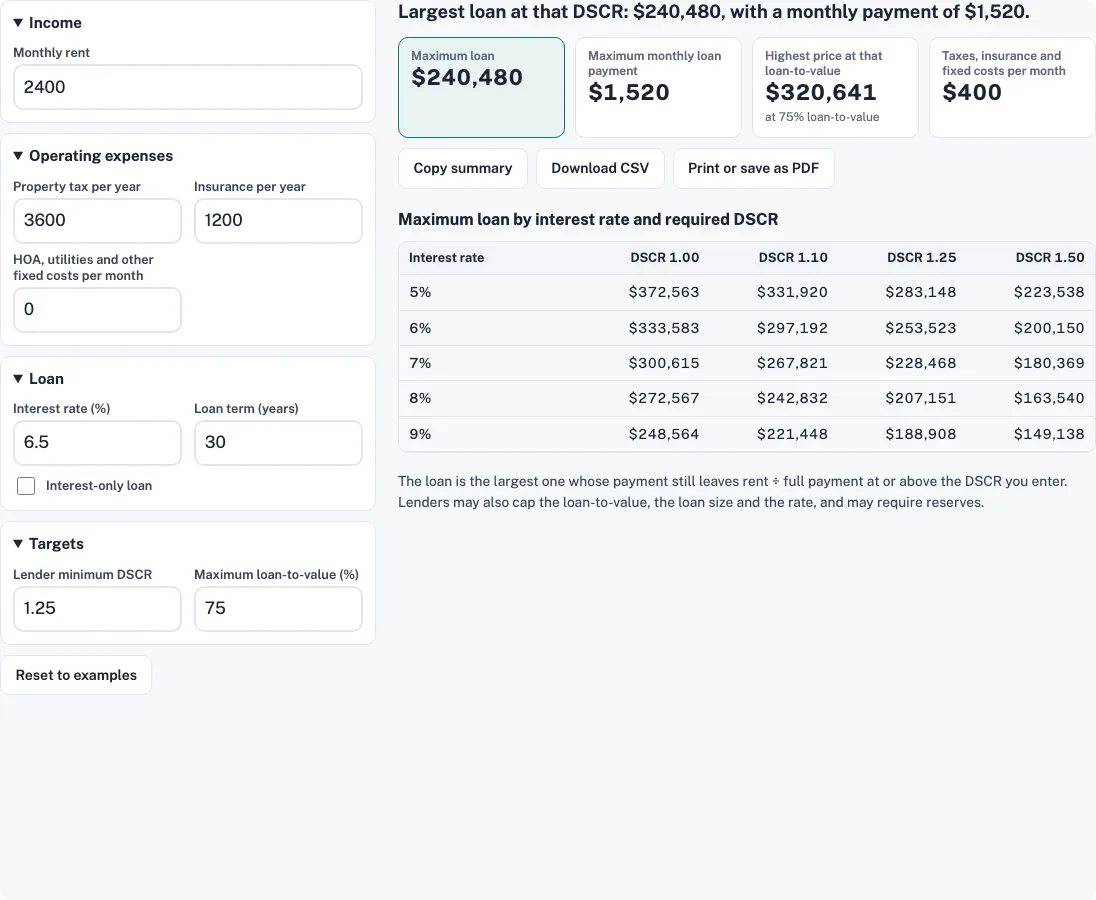
How to use the DSCR loan calculator
- Enter the Monthly rent from a signed lease or a realistic estimate. The example uses 2400.
- Enter the Property tax per year and Insurance per year from the tax bill and your insurance quote.
- Enter the HOA, utilities and other fixed costs per month that your lender counts.
- Enter the Interest rate from the loan quote you have. The tool does not know current rates.
- Enter the Loan term (years). The example uses 30.
- Set Interest-only loan to yes only if you are testing an interest-only quote.
- Enter the Lender minimum DSCR from your lender. The example uses 1.25.
- Enter the Maximum loan-to-value your lender allows, as a percent of the price. The example uses 75.
- Read the Maximum loan and the Maximum monthly loan payment.
- Read the Highest price at that loan-to-value and compare it with the prices you are considering.
The results update live as you type. The buttons Reset to examples, Copy summary, Download CSV and Print or save as PDF work on the current inputs. The page address holds your inputs, so a link to it recreates the same result. The example values are defaults for illustration, not market data or your lender’s terms.
Change one input at a time to see which result moves. The address bar keeps your inputs, so you can bookmark or share a scenario. Reset to examples restores the example values.
How does a DSCR loan qualify a property?
A DSCR loan qualifies the property by its rent rather than by the borrower’s income. The lender asks whether the rent covers the loan payment with the margin set by the DSCR. The calculator works backwards in three steps.
Maximum payment = rent ÷ DSCR − taxes, insurance and dues. With the example inputs, $2,400 ÷ 1.25 = $1,920 of rent available for the payment. Taxes and insurance are $3,600 ÷ 12 = $300 and $1,200 ÷ 12 = $100 per month, and fixed costs are $0. So the loan payment is $1,920 − $300 − $100 = $1,520, which matches the tool’s maximum monthly loan payment.
Then the calculator finds the loan that a $1,520 monthly payment supports at 6.5% for 30 years. That loan is $240,480.
Maximum loan by interest rate and required DSCR
The grid shows the largest loan at each interest rate from 5% to 9% and each required DSCR from 1.00 to 1.50. It uses the example rent and fixed costs. Read across a row to see the loan shrink as the required DSCR rises. Read down a column to see the loan shrink as the rate rises.
| Interest rate | DSCR 1.00 | DSCR 1.10 | DSCR 1.25 | DSCR 1.50 |
|---|---|---|---|---|
| 5% | $372,563 | $331,920 | $283,148 | $223,538 |
| 6% | $333,583 | $297,192 | $253,523 | $200,150 |
| 7% | $300,615 | $267,821 | $228,468 | $180,369 |
| 8% | $272,567 | $242,832 | $207,151 | $163,540 |
| 9% | $248,564 | $221,448 | $188,908 | $149,138 |
The example rate of 6.5% and DSCR of 1.25 falls between the 6% and 7% rows, in the same column. The tool gives $240,480 there, between $253,523 and $228,468.
How is the highest price worked out?
The highest price is the maximum loan divided by the maximum loan-to-value. In the example, $240,480 ÷ 0.75 is about $320,640. The tool shows $320,641, within $1 of that arithmetic. A higher loan-to-value allows a higher price for the same loan, and a lower one allows a lower price.
Do DSCR loans require 20% down?
The down payment depends on the lender, so this calculator does not assume one. It uses the Maximum loan-to-value you enter. The example uses 75, which means 25% down. At the highest price of $320,641, that is $320,641 × 25% = $80,160 of down payment. Ask your lender for its maximum loan-to-value and enter it.
What is the downside of a DSCR loan?
The main downsides are cost and terms. Rates on DSCR loans can be higher than conventional mortgage rates, though this depends on the lender and the deal. Many DSCR loans carry prepayment penalties, which charge a fee if you repay early. Read the rate, fees and prepayment terms in writing before you compare loans, because the calculator does not model them.
What are the current 30-year DSCR loan rates?
This tool does not know current rates, and this page does not quote them. Enter the rate from a lender quote in the Interest rate box. The grid shows how the maximum loan changes from 5% to 9%, which shows a range of outcomes, not a quote.
What else might a lender require?
Lenders may also cap the loan-to-value, the loan size and the rate, and may require reserves. Reserves are cash the borrower keeps after closing. Lenders may also look at the borrower’s credit score. None of these is a fixed rule, so confirm each one with your lender.
Frequently asked questions
How to calculate a DSCR loan?
Divide the monthly rent by the DSCR your lender requires, subtract the monthly taxes, insurance and dues, and the result is the largest loan payment. The calculator then turns that payment into a loan amount at your rate and term. The example gives a maximum loan of $240,480 with a payment of $1,520. Lenders may use a different formula, so ask which one applies.
Do DSCR loans require 20% down?
It depends on the lender, so there is no single answer. Enter the maximum loan-to-value your lender offers in the calculator. Ask your lender for its figure. Your lender may also cap the loan size.
What is the downside of a DSCR loan?
Rates can be higher than conventional mortgage rates, depending on the lender and the deal. Many DSCR loans include prepayment penalties. Check the rate, fees and prepayment terms in writing before you decide.
What are the current 30-year DSCR loan rates?
This calculator does not know current rates. Enter the rate from your lender’s quote in the Interest rate box, and the results will update for that rate. Check the date on any quote you use, because rates change.
What does DSCR stand for?
DSCR stands for debt service coverage ratio, which is a property’s net operating income divided by its yearly loan payments. This calculator works backwards from a chosen minimum DSCR to the largest loan that meets it.
How is the DSCR calculated?
DSCR is net operating income divided by yearly debt service. This page reverses that: the monthly rent divided by the minimum DSCR, minus property tax, insurance and fixed costs, gives the largest monthly payment. The inputs here have no vacancy or management line, so enter a rent figure that already allows for vacancy if you want it reflected.
What is a good DSCR coverage ratio?
This calculator sets no universal target. The example uses 1.25, and the grid shows the maximum loan falling as the required DSCR rises from 1.00 to 1.50. Enter the minimum your lender gives you in the Lender minimum DSCR input.
Related tools
- dscr calculator: use it to check the DSCR for a loan you already have a quote for.
- noi calculator: use it for the commercial NOI-based method.
- rental property calculator: use it to test the cash flow of the loan you find.
- brrrr calculator: use it for refinance-based deals.
- cash on cash return calculator: use it to see the return on your down payment.
- rent vs buy calculator: use it if you are deciding whether to buy at all.