DSCR Calculator
Check debt service coverage by two methods and see the highest price that meets your lender minimum.
Free · runs in your browser · nothing is uploaded
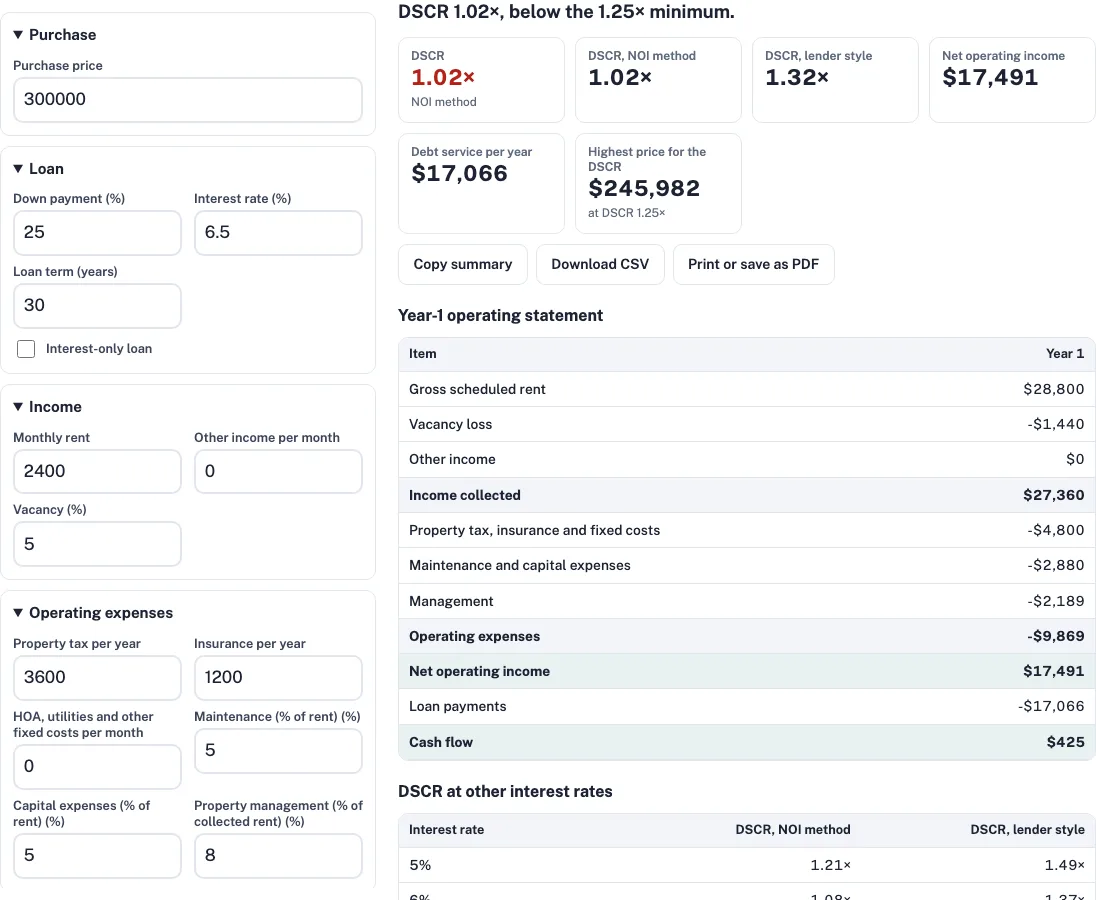
How to use the DSCR calculator
- Enter the Purchase price from your offer or contract.
- Set the Down payment as a percent of the price. The example uses 25.
- Enter the Interest rate and Loan term (years) from your loan quote.
- Set Interest-only loan to yes only if your quote is interest-only.
- Enter the Monthly rent from a signed lease or a realistic estimate, and any Other income per month.
- Enter the Vacancy as a percent of rent you expect to lose. The example uses 5.
- Enter Property tax per year and Insurance per year from the tax bill and insurance quote.
- Enter HOA, utilities and other fixed costs per month, then Maintenance (% of rent), Capital expenses (% of rent) and Property management (% of collected rent).
- Choose the DSCR method: noi or the lender style.
- Enter your Lender minimum DSCR. The highest price result uses this number.
The results update live as you type. The buttons Reset to examples, Copy summary, Download CSV and Print or save as PDF work on the current inputs. The page address holds your inputs, so a link to it recreates the same result. The example values are defaults for illustration, not market data.
Change one input at a time to see which result moves. The address bar keeps your inputs, so you can bookmark or share a scenario. Reset to examples restores the example values.
How do you calculate the DSCR?
DSCR equals net operating income (NOI) divided by annual debt service. Debt service is the total of your loan payments for one year. With the example inputs, NOI is $17,491 and debt service is $17,066, so DSCR is 1.02×.
NOI starts with the rent the property collects and subtracts the cost of running it. The table is the year-1 statement built from the example inputs.
| Item | Year 1 |
|---|---|
| Gross scheduled rent | $28,800 |
| Vacancy loss | -$1,440 |
| Other income | $0 |
| Income collected | $27,360 |
| Property tax, insurance and fixed costs | -$4,800 |
| Maintenance and capital expenses | -$2,880 |
| Management | -$2,189 |
| Operating expenses | -$9,869 |
| Net operating income | $17,491 |
| Loan payments | -$17,066 |
| Cash flow | $425 |
Vacancy is 5% of gross rent: $28,800 × 5% = $1,440. Management is 8% of collected rent: $27,360 × 8% = $2,189. Maintenance and capital expenses are 5% each of rent: $28,800 × 10% = $2,880.
The lender style uses a different ratio. It divides monthly rent by the full monthly payment, which includes principal, interest, property tax, insurance and any HOA dues you enter. In the example, $2,400 ÷ ($1,422 + $300 + $100) = 1.32×. The $1,422 is the $17,066 yearly payment divided by 12, rounded. This ratio leaves out vacancy, maintenance and management, so it comes out higher than the NOI result.
What is a good DSCR rate?
No single DSCR counts as good for every lender, and this calculator cannot know yours. Each lender sets a minimum. Enter that minimum in the Lender minimum DSCR box. A ratio above 1.00 means income covers the payments with money left over. A higher ratio leaves more room for vacancy or a cost increase. In the example, 1.02× clears 1.00 but falls below the 1.25× minimum entered for the example.
What does 1.25 DSCR mean?
A DSCR of 1.25 means income is 125% of the loan payments. The property earns 25% more than it must pay the lender. In the example, a 1.25× ratio needs NOI of $17,066 × 1.25 = $21,333. The property produces $17,491, which is $3,842 short.
DSCR by interest rate
A higher interest rate raises the loan payment and lowers the DSCR, if the price, rent and costs stay the same. The table below changes only the interest rate. The example rate of 6.5% falls between the 6% and 7% rows, and the NOI method gives 1.02× there.
| Interest rate | DSCR, NOI method | DSCR, lender style |
|---|---|---|
| 5% | 1.21× | 1.49× |
| 6% | 1.08× | 1.37× |
| 7% | 0.97× | 1.27× |
| 8% | 0.88× | 1.17× |
| 9% | 0.81× | 1.09× |
Each extra point of rate lowers the NOI ratio by less than the point before it. The drop from 5% to 6% is 0.13, and the drop from 8% to 9% is 0.07.
Can I calculate my DSCR online?
You can estimate your DSCR here with your own rent, costs and loan terms. The result is only as good as the inputs. Take the rent from a signed lease or a realistic estimate, and take the tax and insurance figures from bills and quotes. The calculator does not model lender reserve requirements, so ask your lender which method and minimum it uses before you rely on the number.
What to do when DSCR is below the minimum?
If the ratio is below your lender’s minimum, change one input at a time and watch the result. The usual levers are a larger down payment, a lower purchase price, higher rent and a longer loan term. A longer term lowers the payment, which raises the DSCR. The highest price line works out the price step for you. In the example it shows $245,982 at the 1.25× minimum, which is $54,018 below the $300,000 price entered.
What does this calculator leave out?
It does not know current interest rates, your credit, your reserves or your lender’s loan caps. The two methods can give different answers for the same property. Ask your lender which one it uses, and enter the minimum it gives you.
Frequently asked questions
How do you calculate the DSCR?
Divide net operating income by annual debt service, then compare the result with your lender’s minimum. The example gives $17,491 ÷ $17,066 = 1.02×. Lenders that use the rent method divide monthly rent by the full monthly payment instead.
What is a good DSCR rate?
The right number is your lender’s minimum, and it varies from lender to lender. This calculator gives no universal target. Above 1.00 means income covers the payments, and a higher ratio leaves more buffer. Enter your lender’s minimum in the Lender minimum DSCR box. Lenders also look at other factors, so a minimum alone does not decide approval.
What does 1.25 DSCR mean?
It means income is 125% of the loan payments, so the property earns 25% more than the lender requires. In the example, a 1.25× ratio needs $21,333 of NOI, and the property produces $17,491. Your lender may set a different minimum.
Can I calculate my DSCR online?
Yes, you can estimate it here with your own rent, costs and loan terms. The result is an estimate, so confirm the ratio and the method with your lender before you rely on it. Your lender’s figure is the one that counts for the loan.
What does DSCR stand for?
DSCR stands for debt service coverage ratio. It compares a property’s income with its yearly loan payments, and 1.00 means income exactly covers them.
How much do I need to put down on a DSCR loan?
This page does not set a down payment. The calculator uses the Down payment percent you enter, 25% in the example, and a different down payment changes the loan payment and so the DSCR. Ask your lender which down payment it requires, then enter that percentage.
What if my DSCR is below 1.0?
A ratio below 1.00 means NOI is less than the yearly loan payments, so income does not cover the debt. To raise it, change one input at a time, such as a larger down payment, a lower purchase price, higher rent or a longer loan term. The highest price line shows the most you could pay and still meet your minimum DSCR.
Related tools
- dscr loan calculator: use it to find the largest loan a given DSCR allows.
- noi calculator: use it to build the NOI line by line.
- cap rate calculator: use it for the unlevered return.
- rental property calculator: use it for cash flow and a multi-year projection.
- brrrr calculator: use it for the refinance step.
- cash on cash return calculator: use it for the return on the cash you put in.